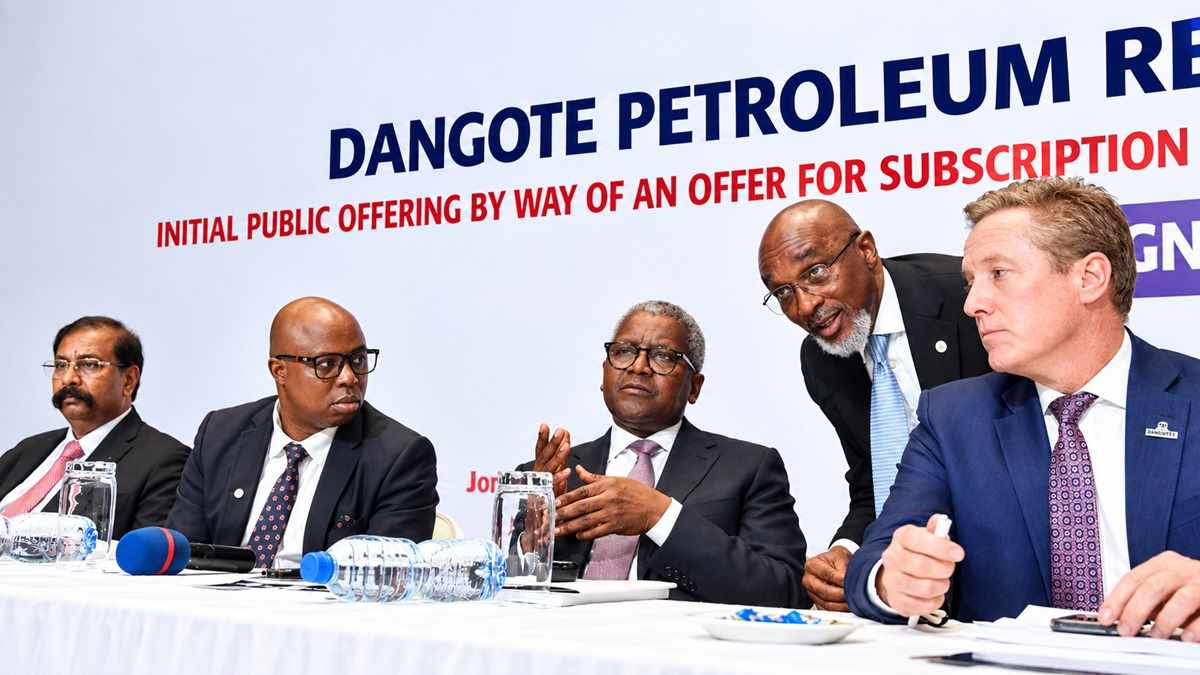
Dangote Refinery N2.15 Trillion IPO Draws Nigeria's Top Dealmakers
Africa's potentially largest-ever public offering, Dangote Refinery's N2.15 trillion IPO, is attracting detailed analysis across multiple dimensions: the dealmaker lineup orchestrating the transaction, how other Dangote Group companies have performed after listing, and the refinery's working-capital model as an overlooked structural advantage. GTI's below-IPO-price valuation of ₦493 per share — reported on September 18 — continues to frame the valuation debate around the offer.
Dangote IPO: the real history lesson is how long patience costs
The Dangote Group's listed siblings are held up as proof this IPO will reward investors. The numbers are real — NASCON up 627% since 2007, Dangote Cement up 666% since 2010.
But read those same numbers the other way. NASCON buyers waited ten years just to get back to their entry price. Dangote Sugar sat 68% below its offer price five years in. The gains came — but only after holding through a decade of losses while the company kept making money.
For the retail investors Dangote is explicitly courting — drivers, cooks, domestic staff buying ten shares at ₦5,250 — a ten-year wait-to-break-even is not a feature. It is a real question about who this IPO actually works for.
3 sources
- How other Dangote Group companies performed after listing · nairametrics.com · T2
- Behind Dangote Refinery’s N2.15 trillion IPO is an army of Nigeria’s top dealmakers · nairametrics.com · T2
- Dangote Refinery’s overlooked advantage could be its working-capital model · nairametrics.com · T2